Risk or Limited Visibility? They Aren't Necessarily the Same Question
Modernization Minute | Quash
There's been a lot of discussion in lending about alternative data and the consumers who may have limited traditional credit histories.
And there's a reason for it.
Federal Reserve research has estimated that millions of U.S. adults are either credit invisible or have thin credit files.
But I think there's an important distinction in that conversation:
Having less traditional credit information available about someone doesn't, by itself, tell you how that person will perform as a borrower.
It tells you that you have less traditional credit information.
Those aren't necessarily the same thing.
And that creates an interesting question for lenders.
When an applicant is difficult to evaluate, what is creating the uncertainty?
Is there information indicating risk?
Is it a policy consideration?
Or is there simply less information available than there would be for someone with a long, established traditional credit history?
You shouldn't assume the answer.
But you can investigate it.
That's one reason alternative sources of information have become part of the broader lending conversation.
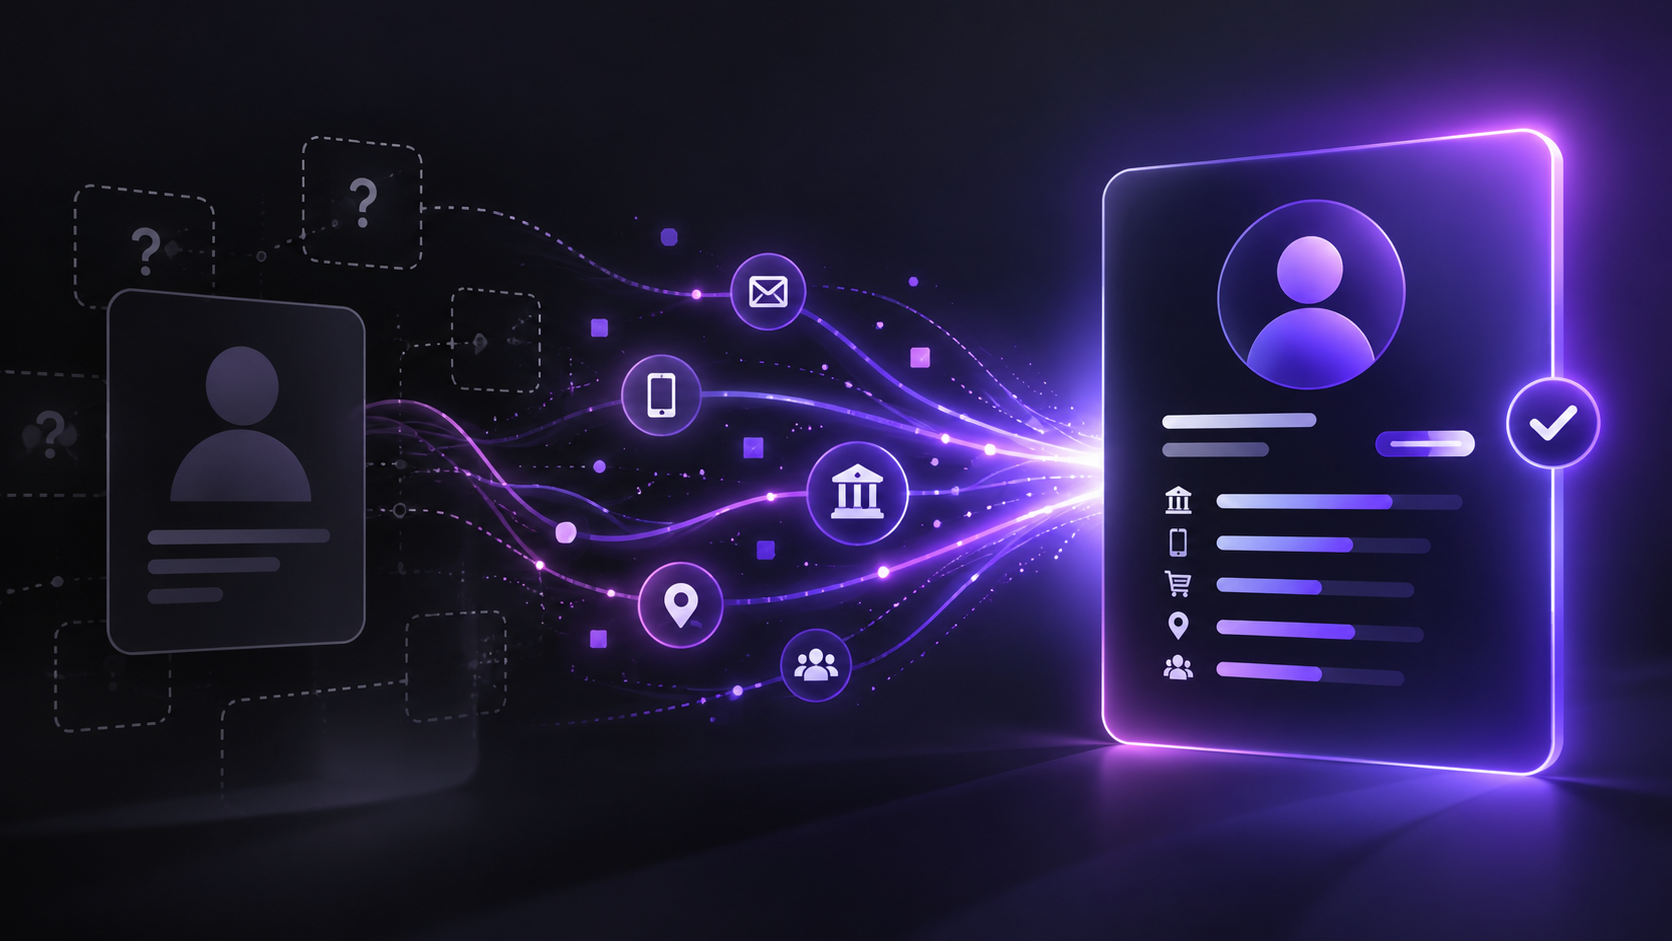
It's also where the Global Inclusion Score fits into what we're building at Quash.
Using an email address and phone number already held by the financial institution, the Global Inclusion Score evaluates more than 300 digital signals to provide an additional layer of digital-identity insight.
The idea isn't that this automatically changes a lending decision.
It's that it gives the institution another piece of information to evaluate.
And from there, the question becomes testable:
Does additional visibility tell us something useful about the populations we serve?
That's your Modernization Minute.
Ruthie Dell is Chief Lending Modernization Officer at Quash. Having worked across financial technology, market research, public relations, and operations, she brings a practical perspective to lending modernization—one that emphasizes human judgment, explainable intelligence, and technology that helps lenders make better-informed decisions rather than simply faster ones.